
A One-Handed Format: Duanju on Home Soil
The story of Chinese short drama begins with a format rather than a firm. Rendered literally, the Chinese term duanju translates as “short drama”, and it describes vertical shows composed at 9:16 for a phone reelshort tv held in one hand. Every episode plays for between one and two minutes, while a single title usually spans 20 to 100 instalments. A trusty stock of premises drives the stories: billionaire and CEO romance, revenge, family conflict and hidden-identity reveals. Each one of those setups can be understood in seconds, and that is crucial when an entire episode has to land before the viewer’s thumb swipes away. In business terms, the format answers a question that regular television hardly ever needed to ask: how does one sell a story in fragments small enough to price one at a time. That same product now meets English-language audiences under other labels, including microdrama, vertical drama and mobile drama. Every stage of the timeline that follows is linked by that pay-per-piece logic.
2020: The NRTA Puts the Genre on the Official Map
The opening milestone is regulatory, not commercial. In 2020, duanju was formally recognized as a genre by the Chinese regulator, the NRTA. Since recognition turns a loose category of online clips into something that can be classified, counted and supervised, that step matters more than it might seem. Tracking a named genre from one year to the next is possible, and that is what allows later statistics about the sector to be compared at all. Commercial success was not ensured by any of this, and for a fledgling industry, a regulator’s attention can cut both ways. Short drama was pushed from the margins of online video toward the status of an industry with its own data. Four years on, the data revealed a sector big enough to stand comparison against the country’s movie theaters.
2024: The Year Short Drama Outearned the Box Office
The domestic numbers for 2024 are the clearest measure of how far the format had come. According to figures published in mid-2025, short drama revenue in China came to 50.5 billion yuan, or about $7 billion. For the first time, the sector earned more than China’s box office, a telling crossover for an industry built on one- and two-minute episodes. That year, studios put out more than 30,000 titles. Estimates put the audience over the same twelve months at 662 million viewers. A business releasing tens of thousands of titles a year is trialing premises at scale, so that volume says as much about the industry’s makeup as the revenue does. It also implies intense competition: every one of those titles is competing for the same few minutes of a viewer’s day. The drive abroad, however, had not waited for this milestone, and by 2024 several Chinese-linked companies were already marketing the same model abroad.
Heading Overseas: The Chinese-Linked Apps Driving the Export Wave
ReelShort came first out of the gate, debuting in August 2022. Behind the app is Crazy Maple Studio of Sunnyvale, California, which is backed by China-based COL Group. DramaBox, built by Beijing Dianzhong Technology and owned by the developer’s Singapore subsidiary, StoryMatrix, followed in April 2023. Singapore New Reading Technology brought out GoodShort in June 2023; the company is reportedly linked to Beijing New Reading Times, though that parent link rests on a less solid source. Alongside 99TV for Southeast Asia, Jiuzhou Culture introduced ShortTV for the United States, Canada and Australia; no rename has been formally announced, but the evidence suggests ShortMax is the same app under another name. Kunlun Tech arrived in September 2024 with DramaWave, published through its Skywork AI business; going by Sensor Tower’s data, its FreeReels app topped global downloads in the first quarter of 2026. What keeps recurring is a Western-facing entity in California, Singapore or Hong Kong fronting a business whose capital or parentage goes back to China. For people who watch dramas online in English, that corporate map is mostly invisible; what they see is a vertical streaming service with a free opening and a paywall.
| Operating company | App | Chinese link | Launch |
|---|---|---|---|
| Crazy Maple Studio (Sunnyvale, California) | ReelShort | China-based COL Group backs it | August 2022 |
| StoryMatrix Pte. Ltd. (Singapore) | DramaBox | Singapore subsidiary of Beijing Dianzhong Technology | April 2023 |
| Singapore New Reading Technology Pte. Ltd. | GoodShort | Reportedly a part of Beijing New Reading Times | June 2023 |
| SHORTTV LIMITED (Hong Kong) | ShortTV / ShortMax | Jiuzhou Culture; the two names appear to be a single app | September 2023 |
| SKYWORK AI PTE LTD | DramaWave | Sits within Kunlun Tech’s Skywork AI business | September 2024 |
| Kunlun Tech | FreeReels | Kunlun Tech’s own app | Not officially confirmed; topped global downloads in Q1 2026 |
| Holywater (founded in Kyiv, 2020) | My Drama | No link; stake held by Fox Entertainment since October 2025 | Spring 2024 |
Dubbed Imports Versus Western Originals
Once the apps were in place, the key strategic question shifted to what to put in them. Jiuzhou’s answer, as reported by China Daily in January 2024, leaned heavily on its home catalogue. Of more than 600 mini-dramas it had produced for overseas markets, about 80 percent were dubbed Chinese adaptations and 20 percent were original overseas productions. That same report pegged the cost of a 70-episode series at $100,000 to $150,000. For a company with a large domestic library, dubbing makes plain sense, because it extends the life of titles that have already been paid for. Western originals reach the audience without a translation layer, but they cost more, with TheWrap citing $150,000 to $300,000 per series shot in eight to ten days. Back in October 2024, TheWrap reported that about 75 percent of ReelShort’s users were women and about half were in the US; that audience, in other words, is specific. With a production team in Los Angeles, DramaBox lists titles such as Fake Dating My Rich Nemesis in its catalogue. Companies without Chinese roots have also been pulled into the originals market. The most prominent is Holywater: in October 2025 its My Drama app secured an equity investment from Fox Entertainment, together with a Fox commitment to produce more than 200 vertical titles over two years.
2025 and 2026: What the Market Trackers Show
By 2025 the overseas business was being followed by several research firms, and their figures differ in instructive ways. According to Sensor Tower, worldwide in-app revenue for short-drama apps reached about $700 million in the first quarter of 2025, with the United States contributing 49 percent, or roughly $350 million. For the full year, Sensor Tower’s data sets in-app revenue at about $2.8 billion to $3 billion, up roughly 115 percent, and different reports of the same dataset cite slightly different totals. Taking a broader view, Omdia puts total microdrama revenue at $11 billion in 2025, $3 billion of it earned outside China, and forecasts $14 billion by the end of 2026. Omdia also expects the US to hit $1.5 billion in 2026, half of all revenue outside China. Media Partners Asia, in estimates reported in August 2026, put revenue outside China at $2.7 billion for 2025, $3.6 billion for 2026 and $9.5 billion by 2031. MPA estimates ReelShort’s revenue at $785 million in 2025 and forecasts $1.05 billion in 2026, with about $40 million in net profit. Its market-share estimates are the most instructive for this timeline: ReelShort with about 29 percent outside China, then DramaBox at 21 percent, DramaWave at 13 percent and GoodShort at 6 percent, roughly 69 percent combined for four apps with Chinese links.
Reading the Timeline Forward
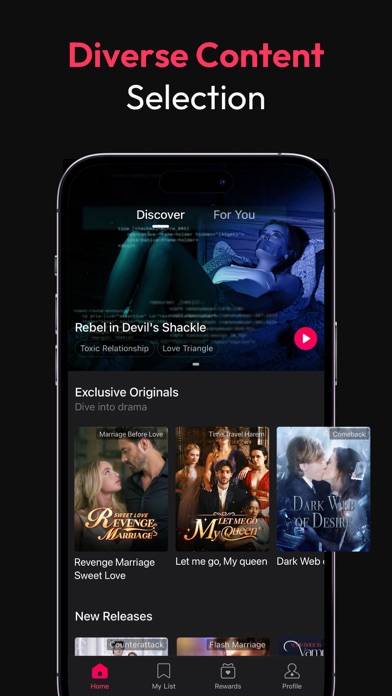
When the milestones are laid end to end, several patterns emerge. First, the overseas business still looks limited next to its origin: Omdia’s figures imply that most microdrama revenue in 2025 was earned inside China. The second is a likely cooling of growth, with Sensor Tower placing the first quarter of 2026 at about $750 million, up 20 percent year on year, after triple-digit growth across 2025. At the top, competition has tightened too: DramaBox and ReelShort each earned about $140 million in that quarter. The way these apps make money has settled into a recognizable shape: across apps such as ReelShort, ShortMax, DramaWave, GoodShort and My Drama, a weekly VIP pass costs about $19.99 in the US App Store as of September 2026, although prices vary by country, platform and promotion. What is most likely to change next is production, because DramaWave, whose annualized revenue topped $700 million by the second quarter of 2026, reportedly generates more than 80 percent of its new releases with AI. The product stays the one duanju producers built at home, a story sold a minute at a time, whether dubbed imports, Western originals or AI output claim the next phase.